UQUAL
FeaturesMortgage ProfessionalsResourcesAcademyCompany
UQUAL

TurnToday'sDeclinedApplicationsIntoTomorrow'sClosedLoans

The loan readiness platform that converts your declined and pre-qualification fallout applicants into mortgage-ready clients through 4-pillar readiness scoring, automated nurturing, and 1-on-1 coaching.

2026 Originator Fallout Recovery Architecture

How Do Mortgage Loan Officers Recapture Credit and DTI Turn-Down Fallout in 2026?

Mortgage loan officers recapture credit and debt-to-income (DTI) turn-downs by routing declined or pre-qualification fallout borrowers into a structured 4-pillar loan readiness program instead of abandoning the file or referring to third-party credit repair shops. By tracking revolving utilization, DTI paydowns, 60-day asset seasoning, and underwriting documentation, originators receive warm handoffs back when borrowers reach target AUS or manual thresholds.

Pipeline Comparison Matrix

Abandoning Turn-Downs vs. Credit Repair Shops vs. UQUAL 4-Pillar Loan Readiness

Read Full 2026 B2B Conversion Guide
Underwriting & Pipeline DimensionAbandoning the Turn-DownThird-Party Credit Repair ShopUQUAL 4-Pillar Loan Readiness
Primary FocusNone ('Call me in 6 months when your score is higher')Single-factor credit bureau dispute letters onlyAll 4 Underwriting Pillars: Credit & Utilization, Back-End DTI, Sourced/Seasoned Cash Reserves, and Income/Tax Documentation
Impact on Automated Underwriting (DU, LPA, TOTAL, GUS)Borrower applies elsewhere or re-pulls prematurely with unchanged findingsActive dispute remarks (> $1,000 non-medical on FHA or material tradelines on DU/LPA) trigger mandatory AUS downgrades or freezesPrepares clean, dispute-free credit, statement-date utilization < 10% to 30%, verified student loan IDR letters, and HUD manual compensating factors
DTI, Student Loan IDR & 60-Day Asset SeasoningNot tracked; borrower often takes on new auto/installment debt while waitingIgnored; borrower returns with a 620 score but fails underwriting over a 54% back-end DTI or unseasoned cash depositsModeled and coached upfront so debt paydowns, IDR servicer letters, and 60-day clean bank statements align before re-pulling credit
Regulatory & Compliance Posture (CROA / RESPA / ECOA)Zero post-Adverse Action educational supportHigh CROA regulatory scrutiny; fee violations and templated mass-dispute letters create reputational risk for referring LOsNon-CROA financial education and 4-pillar loan readiness coaching with transparent RESPA-compliant partner workflows
Originator Pipeline Visibility & Boomerang Return0% visibility; high borrower attrition to competing lenders or online portalsBlack box; no milestone tracking across DTI, reserves, or documentationReal-time Partner Portal milestone tracking with warm boomerang handoff back to the originating loan officer when loan-ready

2026 Loan Officer Fallout Conversion Playbook

Complete 4-pillar borrower incubation matrix, AUS Refer/Eligible rescue workflows, and RESPA/ECOA compliance practices.

Read the B2B Playbook

4-Pillar Readiness Score Calculator

See the 0 to 100 diagnostic index borrowers use to benchmark credit, DTI, reserves, and documentation before a hard pull.

Open Readiness Calculator

2026 Agency DTI & Debt Tradeoff Simulator

Model FHA Manual (31/43 to 40/50), FHA AUS, Conventional, VA, and USDA DTI caps plus student loan IDR rules.

Launch DTI Simulator
Everything You Need to Recover Lost Deals

Powerful Platform Features

UQUAL combines technology, coaching expertise, and proven workflows designed specifically for mortgage professionals, protecting relationships and maximizing pipeline recovery.

Loan Readiness Score

Loan Readiness Score

The industry's proprietary metric tracking real client progress toward mortgage approval across all four underwriting pillars, beyond credit scores alone.

Automated Client Nurturing

Automated Client Nurturing

A self-operating system that engages declined applicants with customized action plans and progress notifications.

Expert Coaching Network

Expert Coaching Network

Professional loan readiness coaches guide clients through credit optimization, debt management, and documentation preparation.

Real-Time Progress Tracking

Real-Time Progress Tracking

Monitor client journeys with full visibility into credit improvements, milestone completions, and readiness indicators.

Seamless Referral System

Seamless Referral System

Quick conversion of declined applications with automated handoff that maintains your lender relationships.

White-Label Solutions

White-Label Solutions

Branded portals and customizable landing pages that position you as the guide on your clients' journey.

Mortgage professional consulting with clients
Loan officer reviewing application
Partner success meeting
Client readiness coaching session
Mortgage team collaboration
Closing day celebration
Lender partnership handshake
FromDeclinetoClose

Turn declined applications into future closings with a simple, automated workflow.

UQUAL transforms your declined applicants into mortgage-ready clients through proprietary scoring, automated nurturing, and expert coaching—protecting your relationships while maximizing recovery rates.

1
Step 01

Refer

Send declined applicants to UQUAL with a single click. Maintain the relationship while we do the heavy lifting of financial preparation.

2
Step 02

Nurture

Clients receive personalized action plans, automated check-ins, and expert coaching to systematically improve their financial profile.

3
Step 03

Track

Monitor real-time progress through your dashboard. Know exactly when clients hit key milestones and approach loan-ready status.

4
Step 04

Close

When clients reach loan-ready status, they return to you—educated, prepared, and ready to close. Turn today's decline into tomorrow's funded loan.

Direct Lender Partner Support

Connect With a UQUAL Partner Representative

Work directly with our national sales leadership and Outside Sales Representatives to configure your branch or team referral workflow, co-branded borrower landing page, and Partner Portal access.

Editorial & Underwriting Review Board
Anthony Iacobucci, National Sales Director at UQUAL

Anthony Iacobucci

National Sales Director

Anthony Iacobucci leads UQUAL's national sales organization. He works directly with mortgage professionals to put a loan-readiness plan behind the borrowers they have to decline, then hand those borrowers back when they are ready to close. His focus is simple: help loan officers keep the relationships they have built and turn today's no into tomorrow's closing.

Book 15 Min With Anthony
Brian Eck, VP of Sales and Marketing at UQUAL

Brian Eck

VP of Sales & Marketing

Brian Eck leads sales and marketing at UQUAL. He works directly with mortgage professionals to put a loan-readiness plan behind the borrowers they have to decline, then hand those borrowers back when they are ready to close. His focus is simple: help loan officers keep the relationships they have built and turn today's no into tomorrow's closing.

Book 15 Min With Brian
Drew Schreter, Outside Sales Representative at UQUAL

Drew Schreter

Outside Sales Representative

Drew Schreter works directly with mortgage professionals to put a loan-readiness plan behind the borrowers they have to decline, then hand those borrowers back when they are ready to close. His focus is simple: help loan officers keep the relationships they have built and turn today's no into tomorrow's closing.

Book 15 Min With Drew
Neil Williams, Outside Sales Representative at UQUAL

Neil Williams

Outside Sales Representative

Neil Williams works directly with mortgage professionals to put a loan-readiness plan behind the borrowers they have to decline, then hand those borrowers back when they are ready to close. His focus is simple: help loan officers keep the relationships they have built and turn today's no into tomorrow's closing.

Book 15 Min With Neil
Juan Bergas, Outside Sales Representative at UQUAL

Juan Bergas

Outside Sales Representative

Juan Bergas works directly with mortgage professionals to put a loan-readiness plan behind the borrowers they have to decline, then hand those borrowers back when they are ready to close. His focus is simple: help loan officers keep the relationships they have built and turn today's no into tomorrow's closing.

Book 15 Min With Juan

Insights to Grow Your Business

View All Articles
2026 Mortgage Credit Report Costs, VantageScore 4.0, and the 65% Fallout Guide for Loan Officers

2026 Mortgage Credit Report Costs, VantageScore 4.0, and the 65% Fallout Guide for Loan Officers

Legacy mortgage credit score fees surged 1,800% from $0.63 in 2020 to $12.00 in 2026, while applicant close rates dropped from 65% to 35%. Learn how loan officers combine VantageScore 4.0 ($1 score fee), single-bureau pre-qual pulls, and UQUAL 4-pillar fallout incubation to cut credit costs by 45%.

Nov 6, 202622 min
Mortgage Turn-Down and Fallout Pipeline Conversion Guide for Loan Officers (2026)

Mortgage Turn-Down and Fallout Pipeline Conversion Guide for Loan Officers (2026)

A complete 2026 playbook for mortgage loan officers and branch managers on converting credit, DTI, and AUS Refer/Eligible turn-downs into closed loans using 4-pillar borrower incubation.

Nov 3, 202621 min
New CFPB Mortgage Disclosure Rules: What Borrowers Need to Know in 2026

New CFPB Mortgage Disclosure Rules: What Borrowers Need to Know in 2026

Stay ahead of the 2026 CFPB mortgage disclosure rule changes. Understand updated TRID requirements and what they mean for your lending compliance workflows.

Jan 6, 20264 min

Loan Officer & Partner FAQ

Answers on fallout incubation, AUS rescue, and compliance.

Reviewed by Anthony Iacobucci (National Sales Director) and Brian Eck (VP of Sales & Marketing).

How do mortgage loan officers recapture credit and DTI turn-down fallout in 2026?

Loan officers recapture credit and debt-to-income (DTI) fallout by replacing informal 'come back in six months' advice with a structured 4-pillar loan readiness incubation workflow. When a borrower falls short during pre-qualification or receives an AUS Refer/Eligible or Adverse Action notice, the loan officer connects the borrower with UQUAL to address credit utilization, back-end DTI, 60-day asset seasoning, and income documentation, then receives a warm handoff back when the file meets underwriting guidelines.

Why does referring mortgage turn-downs to credit repair companies hurt automated underwriting?

Traditional credit repair companies rely on mass credit bureau dispute letters that place active 'Consumer disputes this account' remarks on tradelines. Under HUD Handbook 4000.1 (FHA) and Fannie Mae / Freddie Mac automated underwriting rules, cumulative disputed non-medical derogatory accounts of $1,000 or more force a mandatory downgrade from automated approval to manual underwriting or require dispute removal and a new credit pull. In addition, credit repair ignores DTI ratios, student loan IDR rules, and 60-day bank statement seasoning.

How is UQUAL different from a credit repair company under CROA?

UQUAL LLC is a loan readiness company, not a credit repair organization. UQUAL does not provide credit repair, debt settlement, legal, or tax guidance, and UQUAL is not a lender. Instead of charging fees to dispute credit bureau items, UQUAL provides 4-pillar financial literacy education, interactive readiness and DTI calculators, and 1-on-1 readiness coaching across credit habits, debt-to-income optimization, down payment savings, and underwriting documentation.

What borrower profiles are best suited for UQUAL's 4-pillar partner incubation workflow?

Four borrower segments see the highest conversion from partner incubation: (1) Near-miss credit borrowers in the 540 to 619 range who need utilization timing to cross 580 (FHA 3.5% down) or 620 (Conventional and state DPA grants); (2) High-DTI borrowers (45% to 58% back-end DTI) who need strategic debt paydown sequencing or federal student loan IDR documentation; (3) AUS Refer/Eligible borrowers who need 12-month Verification of Rent (VOR) and 1 to 3 months of PITI cash reserves for manual underwriting; and (4) Self-employed or cash-heavy borrowers who need 60-day bank statement seasoning.

How long does it typically take for a declined or not-yet-qualified borrower to become loan-ready?

Readiness timelines depend on the borrower's primary underwriting blocker. Borrowers blocked by high revolving credit card utilization (>30% to 50% of limits), undocumented student loan IDR payments, or unseasoned cash deposits often prepare within 30 to 60 days (one to two monthly statement cycles). Borrowers building 1 to 3 months of PITI cash reserves, paying down installment debt to lower DTI, or establishing 12 consecutive months of 0x30 housing payment history typically follow a 60 to 180 day roadmap.

How does UQUAL protect the originating loan officer's relationship with the borrower?

When a mortgage professional refers a borrower through the UQUAL Partner Portal or a co-branded landing page, the borrower remains tied to that originating loan officer throughout their readiness journey. UQUAL coaches focus strictly on 4-pillar preparation and never cross-sell competing mortgage products. Once the borrower completes their readiness milestones, UQUAL notifies the originating loan officer for a warm re-application handoff.

How does UQUAL's workflow align with RESPA Section 8 and ECOA Adverse Action rules?

Under the Equal Credit Opportunity Act (ECOA / Regulation B), lenders must issue timely Adverse Action notices stating specific principal reasons for denial. Under RESPA Section 8, lenders cannot pay or receive kickbacks for settlement service referrals. UQUAL operates as an independent consumer financial education and loan readiness platform with zero referral fees or kickbacks paid to loan officers, giving originators a compliant educational resource for borrowers who are not yet ready to qualify.

How can a loan officer, branch manager, or lender partner get started with UQUAL?

Mortgage professionals can register directly through the UQUAL Partner Portal at partner.uqual.com or connect with a dedicated UQUAL Outside Sales Representative (/osr/anthony-iacobucci, /osr/brian-eck, /osr/drew-schreter, /osr/neil-williams, or /osr/juan-bergas) for a 15-minute pipeline walkthrough and co-branded referral link setup.

Standing Legal, Regulatory & Partner Compliance Disclosure (Westminster, CO Headquarters)

UQUAL is a loan readiness company. UQUAL is not a credit repair company and does not provide credit repair, debt settlement, legal, or tax guidance, and UQUAL is not a lender. UQUAL LLC is headquartered at 1499 W 121st Ave #200, Westminster, CO 80234 (Phone: (833) 498-7825). UQUAL does not pay or receive referral fees or kickbacks under RESPA Section 8. Consumers may pull free official credit reports at AnnualCreditReport.com and connect with a HUD-approved housing counselor via the CFPB Housing Counselor Directory.

01
Testimonials
Dallas, TX
Aftertworejections,IfoundUQUAL.Fourmonthslater,Iunderstoodexactlywhatlenderswantedandfinallygotapproved.

Michelle Torres

First-Time Homebuyer

What Our Clients Are Saying •What Our Clients Are Saying •What Our Clients Are Saying •What Our Clients Are Saying •What Our Clients Are Saying •What Our Clients Are Saying •What Our Clients Are Saying •What Our Clients Are Saying •What Our Clients Are Saying •What Our Clients Are Saying •

Grow Your Mortgage Business

Partner with UQUAL to turn declined applicants into closed loans. Our platform handles client nurturing, progress tracking, and readiness coaching - so you can focus on what you do best.

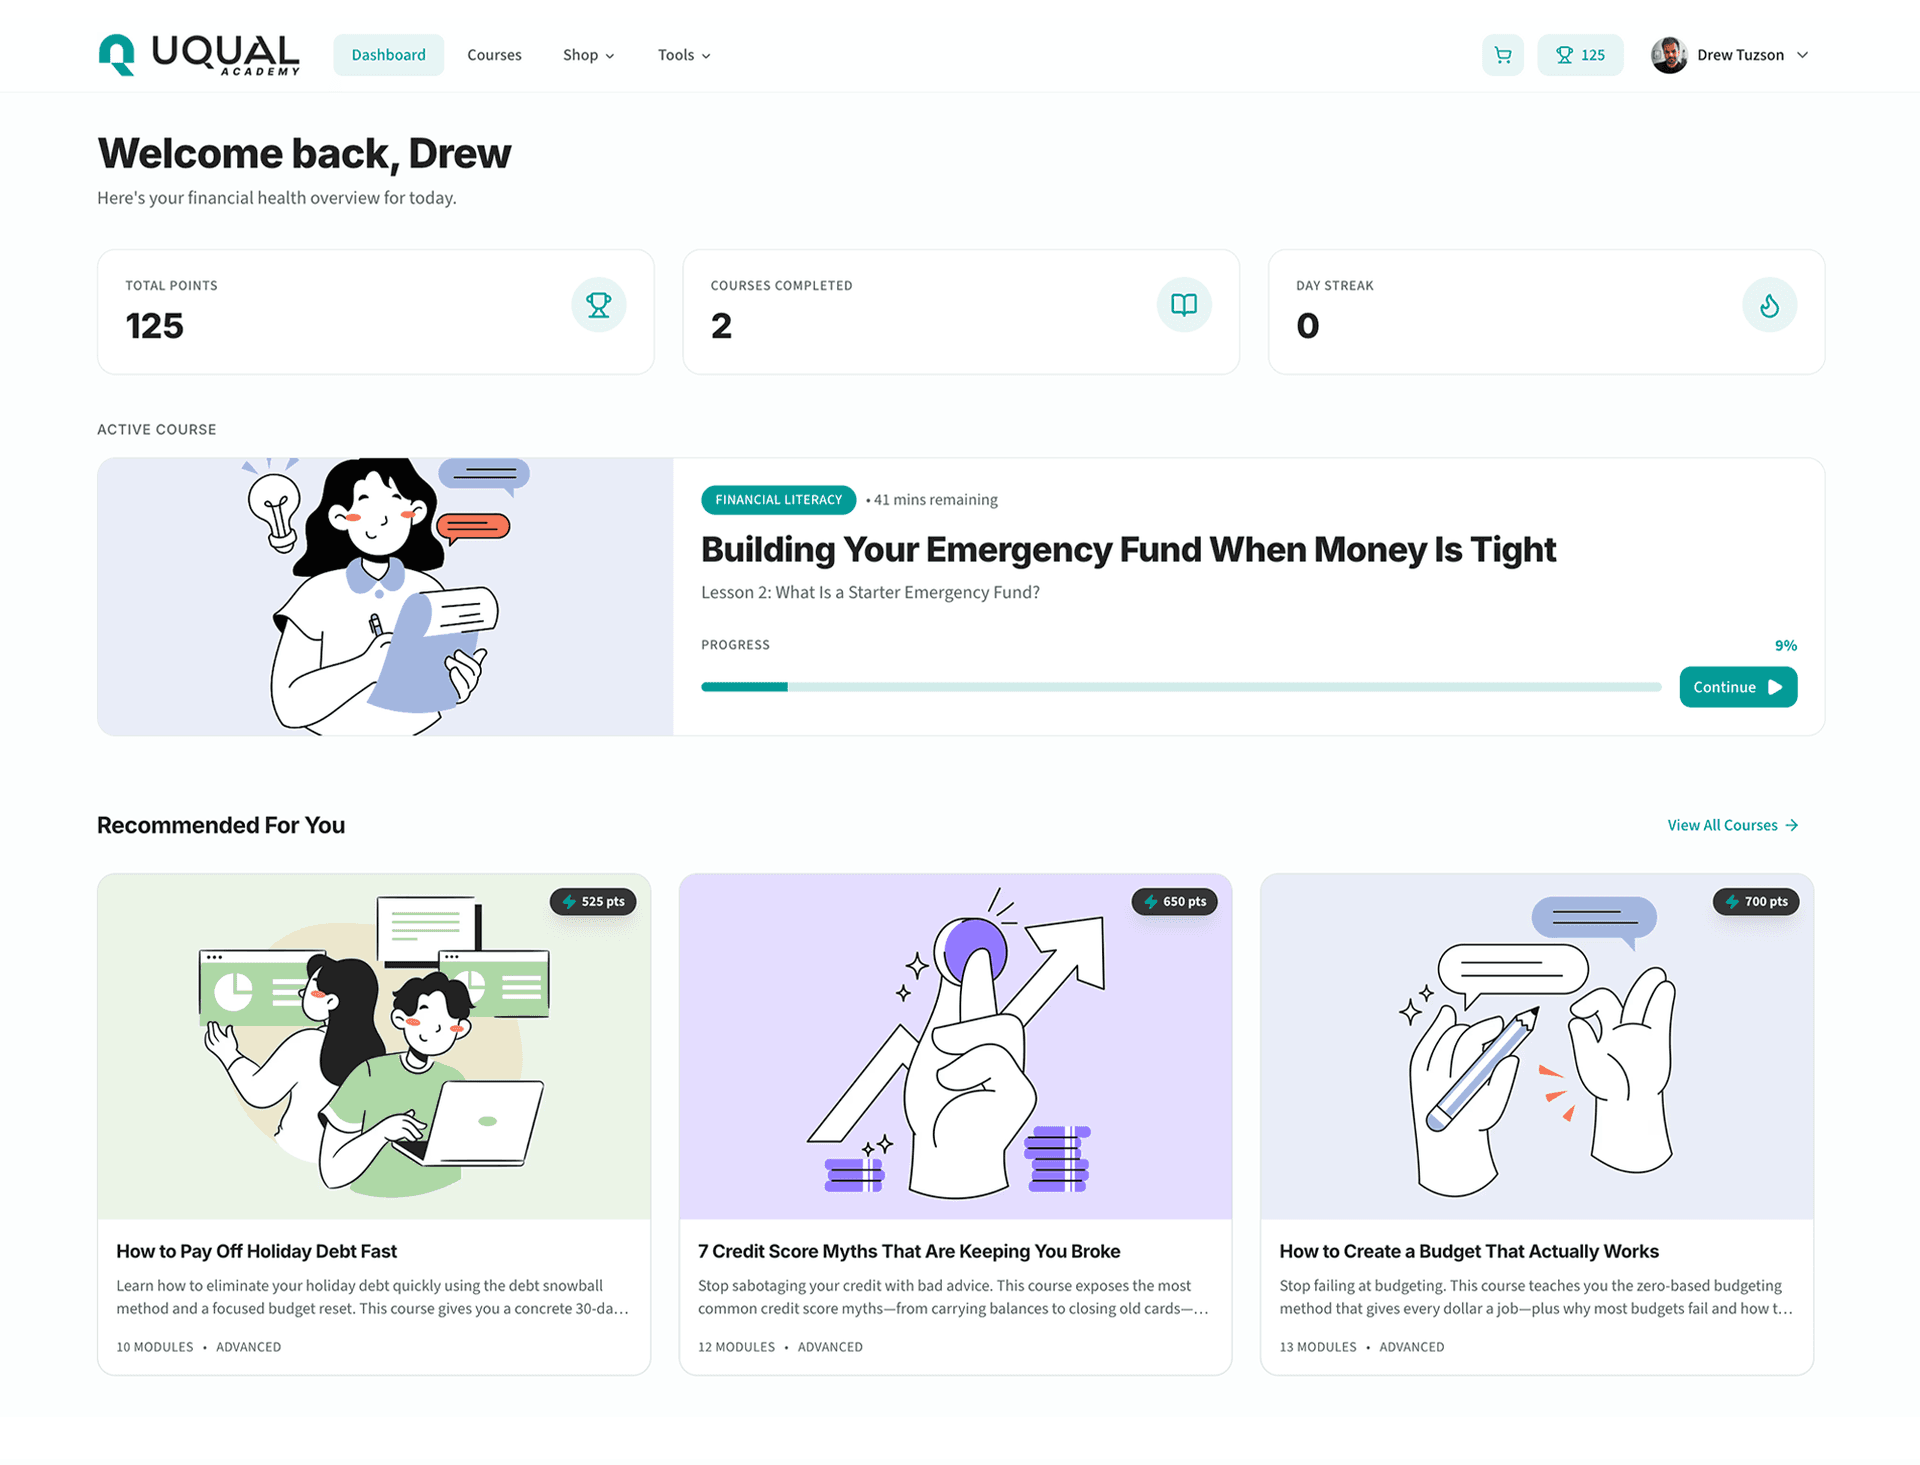
UQUAL Loan Readiness Dashboard Preview
Movement Mortgage
CMG Home Loans
USA Mortgage
Guild Mortgage
CrossCountry Mortgage
First Home Mortgage
Responsive Mortgage
Fairway Independent
Partner 9
Partner 10
Partner 11
Partner 12

© 2026 UQUAL LLC · 1499 W 121st Ave #200, Westminster, CO 80234

UQUAL LLC is a loan readiness company providing educational tools, loan readiness coaches, and customized plans to help consumers prepare to qualify for a loan. UQUAL is not a credit repair company and does not provide credit repair, debt settlement, legal or tax guidance.

Tools

  • Readiness Score
  • Home Affordability
  • Mortgage DTI
  • FHA vs. Conventional
  • Down Payment Help
  • AI & MCP Plugins

Guides

  • Features
  • Mortgage Readiness Hub
  • Student Loans & DTI
  • State Guides
  • Resources
  • Academy

Company

  • About Us
  • Editorial & Review Board
  • For Lenders
  • Partner Portal(opens in a new tab)
  • Careers
  • Contact

Legal

  • Privacy Policy
  • Terms of Service
  • Cookie Policy